The minutes after a car accident are confusing, and the choices you make in them can shape any insurance claim or legal case that follows. This guide explains the practical and legal steps to take, in order.
Some steps protect your health and safety first. Others protect your right to compensation later, because insurers and courts rely on the records created in the first hours and days after a collision.
This article is general information about how the process usually works in the United States, not legal advice for your situation. Rules differ by state, so treat it as a starting point before you speak with a professional.
Check for Injuries and Make the Scene Safe
First, check yourself and your passengers for injuries, and call 911 if anyone is hurt. If the vehicles can be moved safely, shifting them out of traffic reduces the risk of a second collision.
Turn on hazard lights and, if you have them, set out warning triangles or flares. Stay at the scene until responders arrive, because leaving early can bring criminal penalties in most states.
Call the Police and Get an Official Report
Call the police even when the damage looks minor. An officer’s report creates an independent record of the date, location, vehicles and statements involved, which insurers often ask for before they process a claim.
Many states require a report whenever someone is injured or property damage passes a set amount, and the threshold differs by state. Check official state crash reporting guidance before you assume a minor crash needs no paperwork.
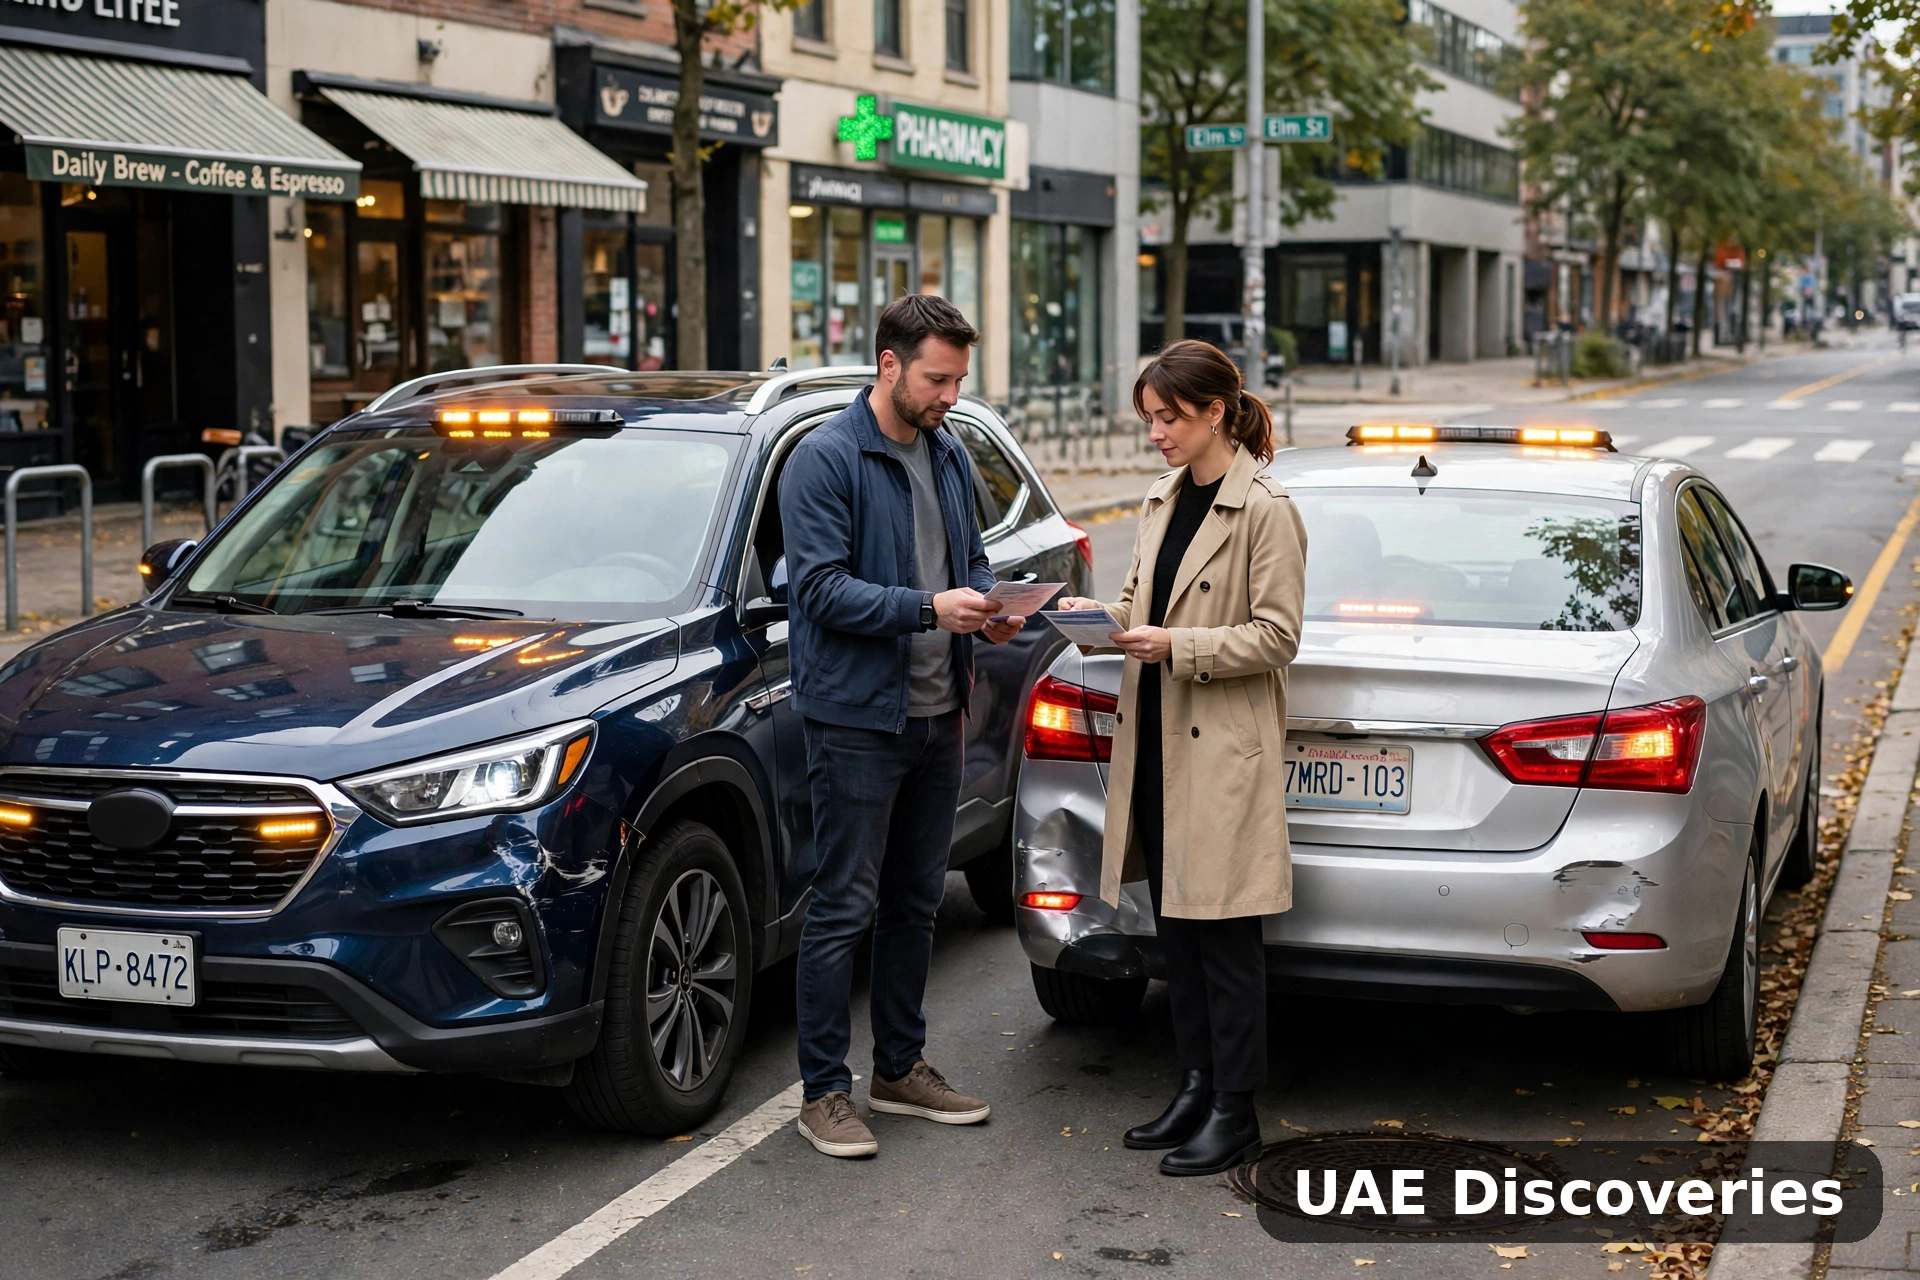
Exchange Information With the Other Driver
Swap names, phone numbers, addresses, driver’s licence numbers, licence plates and insurance policy details with every driver involved. If the driver is not the car’s owner, note the owner’s name and contact details too.
Stay calm and keep the exchange factual and brief. You can be polite without discussing how the crash happened, because early comments about fault can be used later.
Document the Scene While Details Are Fresh
Use your phone to photograph vehicle damage, positions, skid marks, road signs, weather conditions and any visible injuries. Wide shots show context, while close shots capture number plates and specific points of impact.
Write down what you remember as soon as you can, including direction of travel, speeds, signals and what each driver did. Memories fade quickly, and a same-day note carries more weight than a later recollection.
Also collect:
- Names and phone numbers of witnesses
- The responding officer’s name and badge number
- The police report number, once issued
- Names of any towing company or ambulance service
Notify Your Insurance Company Promptly
Tell your own insurer about the crash as soon as you reasonably can, even if the other driver caused it. Most policies require prompt notice, and a long delay can give the insurer grounds to dispute cover.
Stick to the basic facts when you report: when and where it happened, who was involved, and what damage you know about. If you are unsure about an answer, say so rather than guessing.
Be Careful What You Say About Fault
Avoid apologising or accepting blame at the scene, in recorded insurer calls, or on social media. Fault is a legal conclusion based on evidence and traffic law, not something decided in a roadside conversation.
What you say can be quoted back during claim negotiations or in court. If another insurer contacts you for a recorded statement, you can politely decline until you have taken advice about your position.
See a Doctor Even If You Feel Fine
Get a medical check after any significant impact, even when you feel unhurt. Adrenaline can mask pain, and injuries such as whiplash or concussion sometimes appear a day or two later.
Prompt treatment also creates medical records that connect your injuries to the crash date. Gaps between the collision and your first appointment are often used to argue that something else caused the problem.
Keep Records of Every Expense and Loss
Save repair estimates, medical bills, prescription receipts, towing invoices and proof of missed work in one folder. A claim is valued on documented losses, so paperwork you keep now becomes evidence later.
Note smaller costs too, such as travel to appointments or help you had to pay for at home. Individually minor amounts can add up to a meaningful part of the overall claim.
Understand How Fault and Deadlines Vary by State
States apply different fault rules. Most use comparative negligence, which reduces compensation by your share of blame, while a few still bar recovery if you were even slightly at fault.
Around a dozen states instead run no-fault systems, where your own policy pays basic medical costs regardless of who caused the crash. Reading how comparative negligence works helps you understand which system governs your claim.
Every state also sets a deadline, called a statute of limitations, for filing a court case, and missing it usually ends the claim. Look up your state’s court self-help resources early, because some deadlines are short.
When to Speak With a Car Accident Attorney
Consider legal advice when injuries are serious, fault is disputed, an insurer denies or delays your claim, or a settlement offer arrives before treatment ends. Early offers rarely reflect the full cost of recovery.
Many personal injury attorneys offer a free first consultation and work on contingency, meaning their fee comes from any settlement rather than upfront. Ask about fees, timelines and who will handle your case day to day.
Frequently Asked Questions
Do I have to call the police after a minor accident?
Requirements vary by state, but a report is usually required when anyone is injured or damage passes a set threshold. Calling anyway protects you if hidden damage or injuries appear later.
Should I talk to the other driver’s insurance company?
You can give basic contact and vehicle details, but you are generally not required to give a recorded statement to the other insurer. Many people take legal advice before discussing fault, injuries or settlement.
What if the other driver has no insurance?
Your own policy may help if it includes uninsured motorist cover, which many states require or offer by default. Report the crash to police and your insurer quickly, because these claims have strict notice rules.
How long do I have to file a claim?
Insurance claims should be reported within days, while the deadline to file a lawsuit is set by your state’s statute of limitations. That period differs widely, so check it early rather than assuming you have years.
Conclusion
The pattern is simple: protect people first, create an accurate record, notify your insurer, and guard your words until you understand your position. Those steps keep your options open whatever the claim becomes.
If injuries, disputed fault or a denied claim make the situation complex, a licensed attorney in your state can apply the local rules to your facts. Acting early almost always leaves you better protected.