
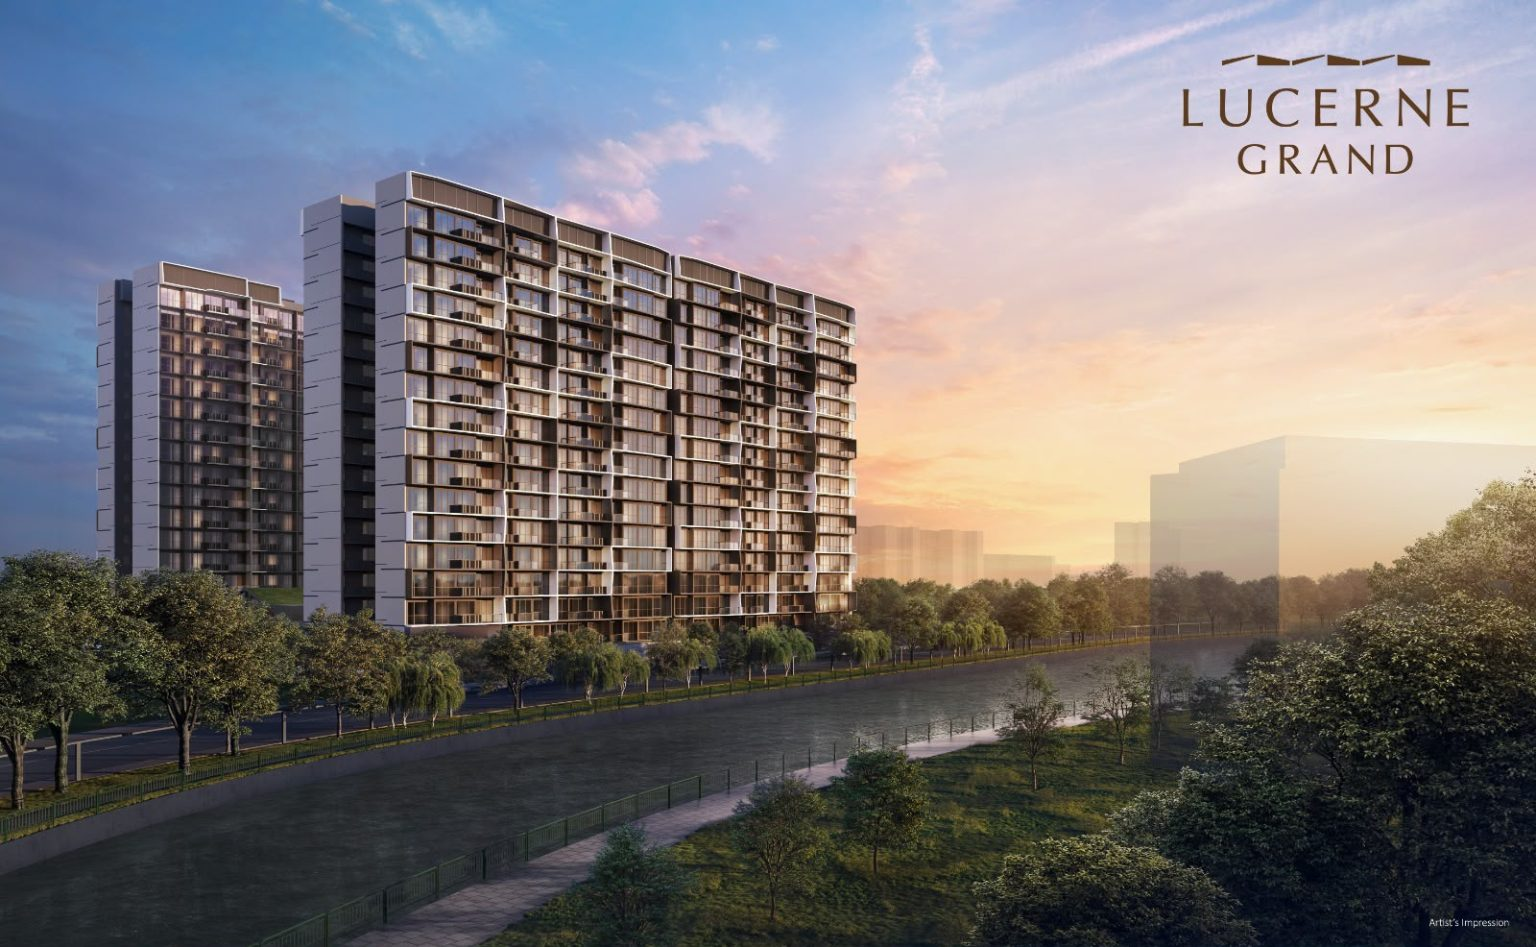
Investing in a luxury property like the Lucerne Grand represents a significant milestone in your financial journey. These high-end developments offer unmatched lifestyle benefits, but they also require a substantial capital commitment. Whether you are eyeing a unit in that prestigious development or planning a purchase in the equally impressive Thomson Reserve, managing your mortgage effectively is crucial for long-term wealth preservation. Securing the property is only the first step; the real challenge lies in structured financial planning. By adopting smart financing strategies, you can easily handle your monthly obligations while keeping your broader investment portfolio healthy and highly productive. Let us examine how to optimize your debt structure for these premium assets.
Assess Your Total Debt-to-Income Ratio
Before committing to a mortgage for a premium home, you must look beyond the purchase price. Lenders evaluate your financial health using the Total Debt Servicing Ratio (TDSR) or similar local debt-to-income metrics. When buying an upscale property like Lucerne Grand, your monthly repayments will likely consume a notable portion of your income. To maintain financial flexibility, aim to keep your total monthly debt obligations, including car loans and credit cards, below 40 percent of your gross monthly income.
Evaluating Hidden Ownership Costs
Owning luxury real estate involves expenses that extend far beyond the principal and interest payments. You must account for maintenance fees, property taxes, insurance premiums, and potential renovation costs. For high-end estates, monthly maintenance fees alone can equal the utility bills of standard apartments. Gathering these figures early helps you calculate the true cost of ownership. If your debt-to-income ratio is too tight, a sudden increase in interest rates or a temporary drop in income can cause immediate financial strain. By keeping a conservative buffer in your debt calculations, you ensure that your investment remains an asset rather than a liability, protecting your lifestyle and your overall net worth. This proactive assessment forms the foundation of any successful real estate investment strategy.
Choose the Right Mortgage Structure
Selecting the appropriate loan package is critical when financing high-value homes such as Thomson Reserve. Buyers often face a choice between fixed-rate and floating-rate packages. Fixed-rate mortgages offer predictability, shielding you from sudden market fluctuations for a set period, usually two to five years. This stability is highly beneficial during periods of rising interest rates, allowing you to plan your household budget with absolute certainty.
Weighing Floating Rate Options
On the other hand, floating-rate loans, which link to market benchmarks like SORA or prime rates, can offer lower initial payments. These are attractive when interest rates are projected to decline. However, they require constant monitoring. If you choose a floating rate for your luxury property, you must possess the financial capacity to absorb potential rate hikes. Some buyers opt for a hybrid structure, combining elements of both to balance risk. Additionally, look for features like offset accounts, where your savings balances reduce the interest charged on your outstanding loan balance. Utilizing these financial instruments effectively reduces the total interest paid over the life of the loan, saving you thousands of dollars that you can redirect toward other wealth-building opportunities.
Implement an Active Refinancing Strategy
Mortgages are not static agreements that you should sign and forget. To manage loans for a premium property like the Lucerne Grand efficiently, you must adopt an active refinancing strategy. Interest rate environments change constantly, and staying with your original lender past the lock-in period can cost you dearly. Generally, lenders offer competitive rates during the initial promotional years, after which the rates step up significantly.
Timing the Refinancing Market
Begin reviewing your loan terms at least six months before your lock-in period expires. Compare the prevailing market rates with your current package to identify potential savings. When refinancing, calculate the associated costs, such as valuation fees, legal fees, and administrative charges, to ensure the switch makes financial sense. If the savings outweigh the transition costs, moving to a new lender or repricing with your current bank is highly advisable. Consistent refinancing every few years can shave years off your loan tenure and reduce your overall interest burden, keeping your capital free for other high-yield investments. Even a minor reduction of half a percent in your interest rate translates to substantial monthly savings when dealing with multi-million dollar property loans.
Establish a Dedicated Mortgage Reserve Fund
A common mistake among luxury property buyers is exhausting all their liquid capital on the down payment. When purchasing in exclusive developments like Thomson Reserve, maintaining liquidity is your best defense against financial instability. A dedicated mortgage reserve fund acts as a financial shock absorber, ensuring you can meet your obligations even during unexpected downturns, career transitions, or business cash flow interruptions.
Determining the Right Liquidity Buffer
Financial advisors recommend keeping at least six to twelve months of mortgage payments in a highly liquid, low-risk account. This fund should remain separate from your daily spending accounts and general emergency reserves. Instead of letting this cash sit idle, you can place it in high-yield savings accounts or short-term government bonds that offer decent returns while keeping the capital accessible. Having this buffer prevents panic selling or taking on high-interest personal loans during tough times. It provides peace of mind, knowing that your high-value asset is secure regardless of short-term economic turbulence, allowing you to focus on growing your primary income sources. This disciplined approach to liquidity distinguishes savvy real estate investors from average buyers.
Align Property Debt with Your Broader Investment Portfolio
Managing property loans should not happen in a vacuum. Your real estate debt must integrate seamlessly with your overall financial portfolio and long-term goals. For instance, if you hold low-yield assets, it might make sense to liquidate them to pay down a portion of your high-interest mortgage. Conversely, if your investment portfolio consistently generates returns higher than your mortgage interest rate, keeping the loan active while investing your surplus cash is the smarter financial move.
Balancing Leverage and Risk
Leverage is a powerful tool in real estate, but excessive leverage increases your vulnerability. Regularly review your asset allocation to ensure you are not overly concentrated in property. If a large portion of your net worth is tied up in your home, you may face liquidity challenges later in life. Balancing your mortgage payments with contributions to retirement accounts, equities, and other liquid investments ensures a diversified financial foundation. By treating your property loan as one component of a holistic financial plan, you can maximize your wealth accumulation while minimizing unnecessary exposure to market shocks. This balanced approach ensures steady progress toward all your financial milestones.
Conclusion
Managing substantial mortgages for prestigious properties requires strategic planning, constant vigilance, and disciplined execution. By understanding your true debt capacity, choosing the right mortgage structures, and maintaining a robust reserve fund, you can confidently build long-term equity without compromising your financial security. Remember to review your loan packages regularly and align your debt management with your broader investment objectives. With these smart financing tips, your investment in luxury real estate will serve as a strong foundation for your family’s enduring wealth and financial freedom. Taking control of your debt today ensures a more prosperous and stress-free tomorrow.
